Her Own Compass shares financial education and personal experience, not individualized financial, investment, or tax advice. Every situation is different, so please consult a qualified professional before making major money decisions.
Paying off debt is mostly a long stretch of months where nothing visibly changes. A debt payoff tracker fixes that by turning an invisible balance into something you can color in, cross off, or watch drop. One woman on r/DaveRamsey kept a padded savings account instead of attacking 64,000 dollars in student loans because the cushion felt safer. The day she paid the loans off anyway, she still had 19,000 dollars left. Seven tracker formats below, matched to what actually keeps a person going.
The short version: The debt payoff tracker ideas that hold up over years are a color-in chart, a debt thermometer, an envelope grid, a spreadsheet with an interest column, a payoff calendar, a snowball card deck, and a single sticky note. Pick by what you need to see, not by what looks best.

Save this for later
You will want this again. Pin it to your planning board so it is one tap away when you need it.
Pin it for laterWhy does a debt payoff tracker actually change anything?
A tracker works because debt payoff has no natural feedback, and humans quit tasks that give none. Your balance drops once a month, in an app you have to open on purpose, by an amount that looks small next to the total. Nothing about that arrangement is built to keep you going.
The mechanism is progress visibility, the same reason a loading bar feels better than a spinning circle. When effort produces a visible mark, the brain treats the next unit of effort as cheaper. A tracker on the fridge converts a 36-month project into 36 small completions, and each completion is what carries you to the next one.
There is a second, less comfortable reason. A tracker makes the interest visible, and interest is the number most payoff guides skip until it is too late to plan around.
The number your debt payoff tracker should show first
Before the first extra payment, find out how much of your monthly payment never touches the balance. That figure decides whether your plan is a payoff plan or a very expensive holding pattern.
In a r/DebtAdvice thread, a commenter ran the arithmetic for a single mother of three carrying 91,000 dollars across credit cards, personal loans, and a car loan at an average 13 percent APR, and put it bluntly: “Are you aware that $91k of debt at 13% is just about $1k a month in interest alone?” She had 1,100 dollars a month available. That left roughly 100 dollars touching principal. The same commenter projected 7 to 8 years of repayment and almost 30,000 dollars paid in interest.
Do you need to run that math yourself? Yes, once, before choosing a tracker format. Multiply each balance by its APR, divide by 12, and add the results. That total is your monthly interest, and any tracker worth using has a column or a line for it. The Federal Reserve’s G.19 consumer credit release publishes current average rates if you want to see where yours sits.
Three visual debt payoff tracker ideas for people who need to see progress
Visual trackers work best for anyone who has quit a payoff plan before, because they put the win where you cannot avoid seeing it. All three cost under 5 dollars to set up.
The color-in chart
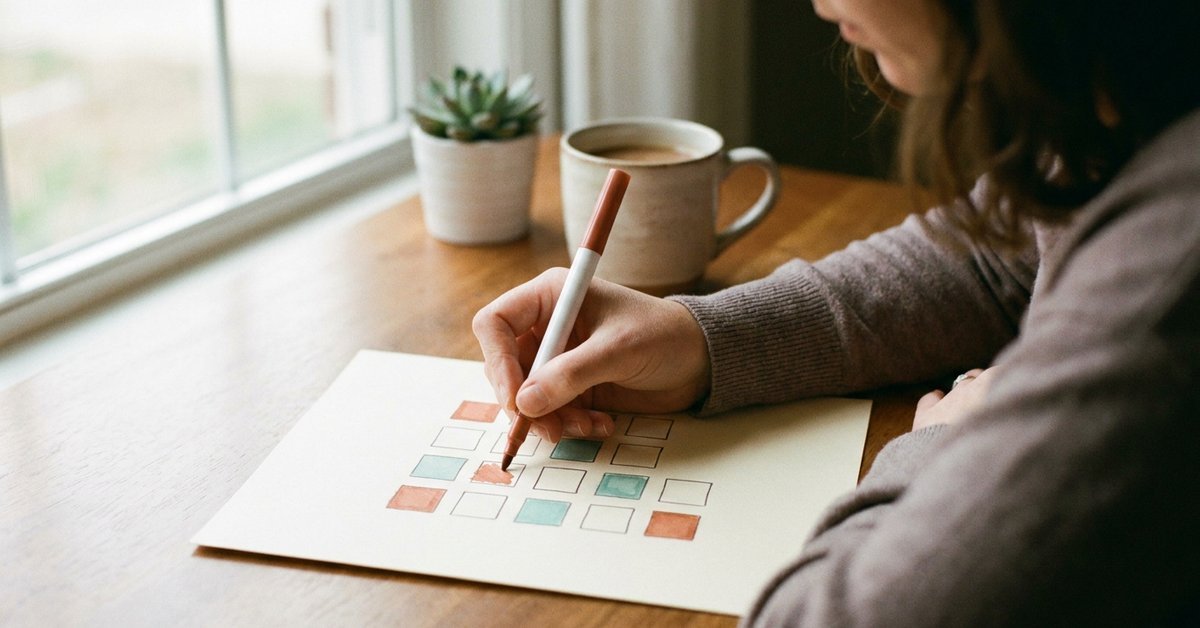
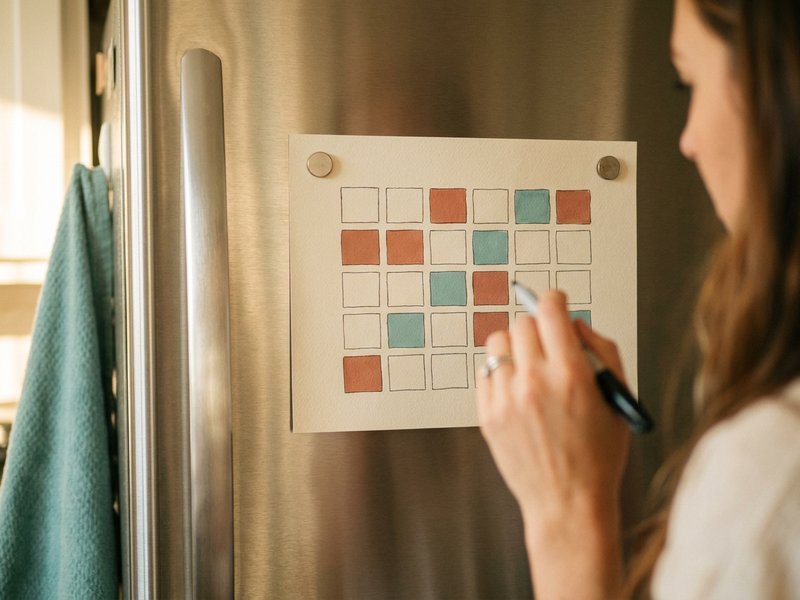
Draw or print a grid where each square equals a fixed amount, usually 50 or 100 dollars, and fill one in per payment. A 12,000 dollar balance at 100 dollars a square is 120 squares, which reads as a real distance rather than an abstract number. Keep it somewhere you pass daily: the fridge, the inside of a cabinet door, the back of the bathroom door.
The debt thermometer
A single tall column you shade from the bottom up, borrowed from fundraising campaigns. It suits one large balance better than several small ones, and it is the format most likely to survive a bad month, because a half-shaded thermometer still looks like something you built.
The envelope grid
Number a set of envelopes with amounts, then remove one each time you pay that amount toward the debt. It is the sinking-fund idea run in reverse, and the physical act of removing an envelope does more for motivation than updating a cell. If you already run sinking funds, the sinking fund categories guide covers the same envelope logic on the saving side.
Three number-based trackers for people who trust math more than color
These three show you the interest, the payoff date, and the order of attack, which is what a visual chart cannot do.
The spreadsheet with an interest column
Four columns is enough: balance, APR, minimum payment, and monthly interest. Update it once a month on the same date. The value is not the arithmetic, which any calculator does; it is watching the interest column shrink, because that column is the one that proves the plan is working.
The payoff calendar
Write the projected payoff month for each debt on a 12 or 24 month calendar, then move the date earlier every time you make an extra payment. Moving a date from November to September is a bigger emotional hit than watching a balance drop by 400 dollars, and it is the same event.
The snowball card deck
One index card per debt, ordered smallest balance to largest, and you physically tear up a card when a debt is gone. This is the avalanche or snowball decision made tangible. Order by balance for momentum, or by APR to pay the least interest overall. The FTC’s guide to getting out of debt explains both approaches without selling you anything.
The seventh tracker: one sticky note
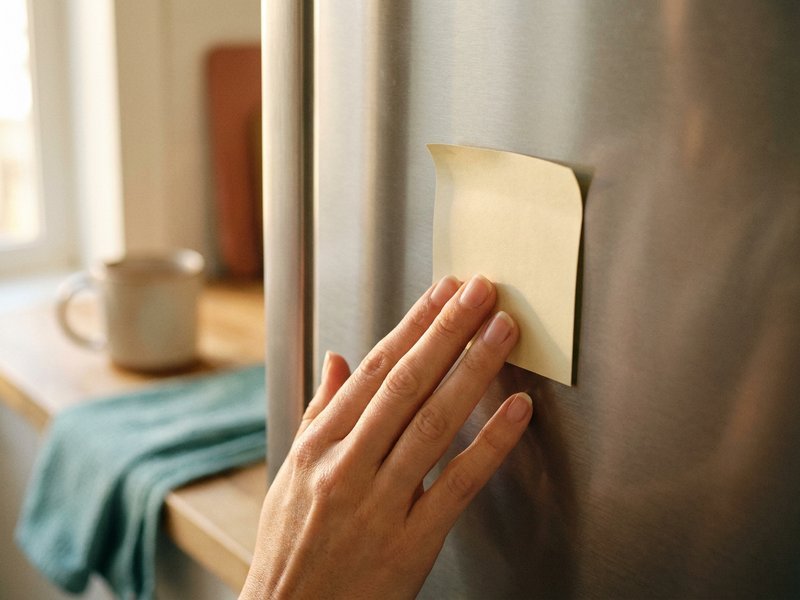
Write today’s total balance on a sticky note, and replace it with a new one each month. Nothing else. No app, no printout, no color scheme.
This is the tracker for anyone who has abandoned three elaborate systems already. The elaborate system is usually the problem: a tracker you have to maintain becomes one more chore competing with the debt itself. A stack of old sticky notes in a drawer turns out to be a surprisingly good record, and the descending numbers tell the whole story at a glance.
Which debt payoff tracker fits you
Pick by the reason your last plan stopped, not by which tracker looks best on Pinterest. Each of these fails in a specific way, and knowing the failure mode in advance is what keeps you from starting over in March.
| Tracker | Best for | Where it falls short |
|---|---|---|
| Color-in chart | Quitting from boredom | Hides the interest cost entirely |
| Debt thermometer | One large balance | Awkward with 4 or more debts |
| Envelope grid | Needing something physical | Cash-based, clumsy for card autopay |
| Spreadsheet | Wanting the real math | Easy to abandon after a bad month |
| Payoff calendar | Long timelines, 3 years plus | Slow feedback between milestones |
| Snowball cards | Several small debts | Nothing to look at day to day |
| Sticky note | Having quit every system | No detail, no interest visibility |
Running one visual and one numeric together covers both gaps. A chart on the fridge and a four-column spreadsheet updated monthly is the pairing that survives the longest on a single income.
What to do when the tracker stops moving
A flat month is a data point, not a failure, and the fix is almost always the payment amount rather than the plan. Trackers stall for three reasons: an unplanned expense, an interest load that eats the payment, or a payoff order that put the slowest debt first.
Sometimes the answer is selling the asset attached to the debt. A woman writing in r/povertyfinance spent two years dragging herself out of debt after damaging her credit between 18 and 24. With a few thousand dollars left, she sold her truck outright and used it to close the balance instead of stringing out payments for another year. Her credit sat at 572 afterward, low but climbing, and she owed nothing to anyone.
What if the numbers genuinely do not work? Then the tracker has done its job by telling you early. Nonprofit credit counseling through a member agency of the National Foundation for Credit Counseling is free or low cost for the first session, and it is a different thing from a debt settlement company that charges fees. This is education rather than a recommendation for your situation, and a licensed counselor is the person to run your actual numbers.
Setting up your tracker this week
Twenty minutes, once, and the maintenance is two minutes a month.
- List every debt with its balance, APR, and minimum payment. Statements or the lender app both work.
- Calculate this month’s total interest: balance times APR, divided by 12, added up across all debts.
- Choose an order: smallest balance first for momentum, highest APR first for the lowest total cost.
- Pick one visual tracker and one numeric tracker from the seven above.
- Set a monthly date to update both, the same day your largest payment posts.
The money for the extra payment has to come from somewhere named. A spending plan that assumes one income is where most of it appears, which is what the 12 budget categories for a one-income household and the guide to stretching one income further both work through. The rest of the debt payoff guides hub covers method rather than motivation. The reading list for a debt-free journey is coming next.
Progress on paper rarely matches how long it felt. One woman answering on Quora finally paid off her divorce lawyer’s bill years after the paperwork ended: filed in 2018, the last filing running until 2021, after a marriage of 5.5 years. Paying it off took longer than the marriage had lasted. She does not call herself financially recovered, and she has something she never had through all those freelance years: a steady salary and real benefits.
That is what a finished tracker actually looks like. Not a dramatic finish, just a smaller number than last month, written down where you can see it. You are funding this, one square at a time.
Found this helpful? Pin this guide so you can come back to it anytime.
Frequently Asked Questions
What is a debt payoff tracker?
A debt payoff tracker is any visual or numeric record that shows your balance dropping over time, from a color-in chart to a four-column spreadsheet. Its job is feedback rather than math: debt payoff gives almost no natural signal of progress, and a tracker supplies one every month.
How do I make a debt payoff tracker that I will actually keep using?
Pick by the reason your last plan stopped. If you quit from boredom, use a color-in chart where each square is 50 or 100 dollars. If you quit from confusion, use a spreadsheet with an interest column. Running one visual and one numeric together covers both failure modes.
Is a debt payoff tracker worth it on one income?
Yes, and the interest column is the reason. Seeing how much of each payment never touches the balance changes which debt you attack first, which is worth thousands over a multi-year payoff. Setup takes 20 minutes and maintenance runs about two minutes a month.
Should I talk to a credit counselor about my debt?
If your minimum payments are barely covering interest, yes. A counselor at a nonprofit agency affiliated with the National Foundation for Credit Counseling reviews your numbers for free or low cost, which is different from a debt settlement company that charges fees. This article is education, not individualized advice.